

The “Barbarous Relic” That Refuses to Die: Gold at the Crossroads
John Maynard Keynes described the gold standard—not gold itself—as a “barbarous relic”. Yet the metal has returned to the centre of global finance. After the LBMA gold benchmark reached a record $5,501.70 an ounce on 29 January 2026 before retreating sharply, an old question has acquired new relevance: what function can gold serve in a modern financial system?
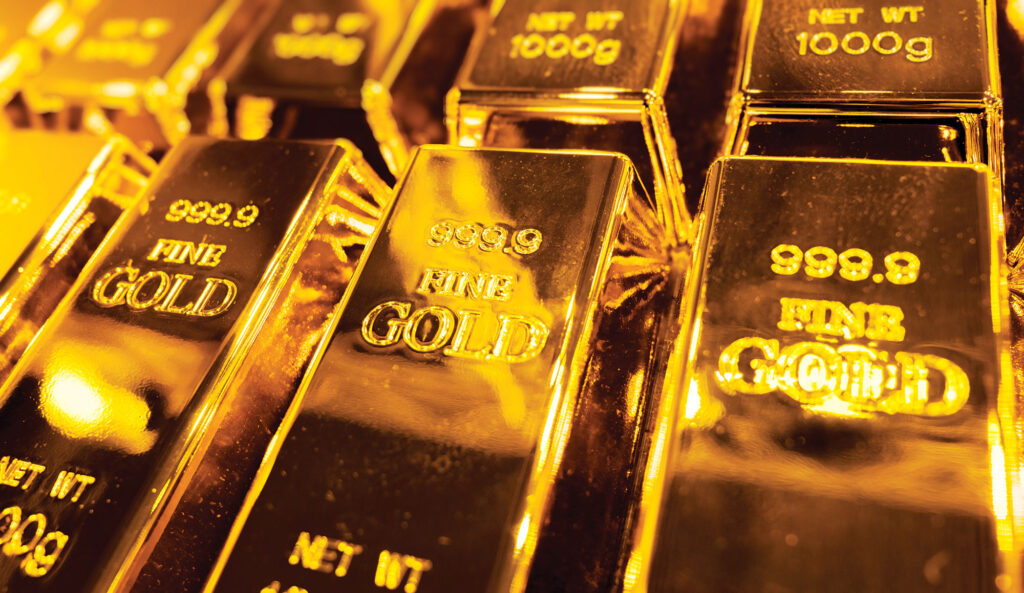
Gold has repeatedly survived predictions of its irrelevance. In 1999, with the metal trading near $250 an ounce, the UK government announced a programme that would sell more than half of Britain’s gold reserves between 1999 and 2002. The prevailing view was that gold had become a monetary relic.
More than a quarter of a century later, central-bank purchases remain historically elevated, gold’s share of official reserves has increased and the January 2026 peak stood at more than twenty times the late-1990s price.
That increase in gold’s share of reserves requires context. Much of it reflects the rise in the market value of existing holdings rather than the acquisition of additional metal. Central banks nevertheless purchased an estimated 863 tonnes during 2025. That was below the exceptionally high level recorded in 2024, but still substantial by historical standards.
The revival has reopened a familiar debate. Gold bullion produces no contractual income and has underperformed productive assets over very long periods. Yet it continues to attract demand when confidence in currencies, governments or financial systems weakens.
The relevant question is therefore not whether gold is inherently superior to other assets. It is what role the metal has played historically, how its market is changing and whether its distinctive characteristics remain relevant.
Five Thousand Years of Preservation
The first lesson from the historical record is that gold is not conventionally regarded as a growth asset. Its reputation rests principally on the preservation of purchasing power over extended periods rather than the compounding of income.
Economists Claude Erb and Campbell Harvey have examined what they call the “golden constant” hypothesis: the proposition that gold’s real value tends to return towards a long-term range. Their research also demonstrates the limits of the idea. Gold can remain substantially above or below estimates of fair value for prolonged periods, making it an unreliable short-term inflation hedge.
Long-run financial data illustrate the distinction between preservation and wealth creation. Research associated with Jeremy Siegel has found that US equities generated materially higher inflation-adjusted returns than gold over extended periods. Productive assets can reinvest earnings and compound. Gold cannot do so by itself.
For much of history, however, gold was not an investment in the modern sense. It functioned as money or as the asset against which currencies were valued. Under the classical gold standard, its principal purpose was to support monetary convertibility and constrain the issuance of currency.
The modern market emerged through a sequence of political decisions. In the United States, measures introduced under Franklin Roosevelt in 1933 restricted most private monetary ownership of gold. The official price was subsequently raised from $20.67 to $35 an ounce. In 1971, Richard Nixon suspended the dollar’s official convertibility into gold, bringing the Bretton Woods system to an end.
Once gold was free to trade independently of a fixed currency price, its modern market characteristics became more visible.
The 1970s provided the first major example. As inflation accelerated and confidence in monetary stability weakened, gold rose from the official price of $35 an ounce to $850 in January 1980. The advance was extraordinary, but so was the reversal. As the US Federal Reserve under Paul Volcker tightened monetary policy and real interest rates rose, gold entered a prolonged decline and lost much of its inflation-adjusted value.
A similar pattern appeared after the global financial crisis. Gold advanced strongly through 2011 amid quantitative easing, sovereign-debt concerns and fears of monetary instability. It then entered another lengthy period of weaker performance.
The historical record suggests that gold has often benefited when confidence in monetary and political institutions has come under pressure. It has also experienced deep corrections and long periods of stagnation when financial stability and confidence returned.
The Return of the Central-Bank Buyer
One distinguishing feature of the current cycle is the importance of official-sector demand.
The freezing of Russian central-bank assets following the invasion of Ukraine reinforced concerns among some reserve managers about sanctions and access to foreign-currency holdings. Assets held within the international financial system can offer liquidity and income, but access may be affected by political or legal decisions.
Gold offers a different set of characteristics. Directly held physical bullion is not the liability of another government or financial institution. It can therefore provide reserve diversification, although its storage, security and liquidity arrangements still require careful management.
Central-bank purchases remained historically high through 2025, even though they slowed from the record levels of the previous year. Recent reported buyers have included Poland, China, Kazakhstan and Brazil. The motivations and scale of purchases differ between countries, and not all changes in official reserves are disclosed immediately.
Central banks are also different from conventional investment managers. Their objectives can include liquidity, currency diversification and resilience during periods of financial or geopolitical disruption. They are not necessarily attempting to maximise short-term investment returns.
Official demand has consequently become a significant structural feature of the gold market, rather than its sole driving force. Investment flows, jewellery consumption and household purchases—particularly in major Asian markets—continue to influence demand.
Nor does official buying eliminate volatility. After reaching its January 2026 record, gold retreated markedly by the middle of the year. The correction coincided with shifting inflation expectations, movements in bond yields and reassessments of the opportunity cost associated with holding a non-income-producing asset.
The episode demonstrated that gold can serve as a strategic reserve asset while still behaving as a volatile market instrument.
Why Gold Remains Relevant
Gold is frequently examined for its potential diversification characteristics. Its price can respond differently from equities and bonds during periods of currency stress, geopolitical conflict or declining confidence in financial institutions.
This does not make it a universal hedge. Gold can fall during inflationary periods, particularly when real interest rates rise or investors prefer assets that generate income. It can also underperform for many years. Its defensive characteristics are conditional rather than automatic.
Interest in gold tends to strengthen when assumptions supporting conventional portfolios are questioned. Government debt has increased across major economies, fiscal deficits remain elevated and geopolitical fragmentation is affecting trade, capital flows and reserve management. The wider use of sanctions and financial restrictions has also made reserve diversification a strategic consideration for a number of governments.
These developments unfold over years rather than quarters. They may support demand for gold, but they do not guarantee price appreciation. The same historical record that demonstrates gold’s durability also warns against treating recent momentum as evidence of permanent outperformance.
Gold prices are influenced by many overlapping forces: central-bank activity, jewellery demand, investment flows, currency movements, market liquidity, inflation expectations and interest rates. No single factor explains every market cycle.
The Interest-Rate Constraint
The opportunity cost of holding gold remains an important consideration. Physical bullion generates no interest or dividend, so higher real interest rates can increase the relative attraction of cash and government bonds.
The relationship is not perfectly stable. Gold may sometimes rise alongside interest rates when geopolitical or financial risks dominate. Nevertheless, monetary policy and inflation-adjusted yields have historically influenced the willingness of investors to hold a non-income-producing asset.
The next phase of the market will therefore depend partly on the path of inflation and interest rates. Lower real yields could make gold comparatively more attractive, while persistently high real yields could create a less supportive environment. Central-bank purchases and geopolitical demand may operate alongside these forces rather than override them.
Forecasts for gold vary widely, reflecting uncertainty about monetary policy, official-sector demand and international risk. That dispersion is itself instructive. Short-term price targets have often proved less dependable than analysis of the structural forces affecting supply and demand.
Not All Gold Exposure Is the Same
References to “investing in gold” can conceal important differences between financial instruments.
Direct ownership of bullion provides exposure to the metal itself, but involves dealing spreads, secure storage, insurance and custody. Gold-backed exchange-traded products may be easier to trade, but introduce management charges, legal structures and reliance on intermediaries.
Futures and other derivatives involve leverage, collateral requirements and potentially significant short-term volatility. Shares in gold-mining companies are productive securities that may generate cash flow, but they also carry operational, political, environmental and management risks. Their performance can diverge considerably from the price of bullion.
Jewellery and collectible coins present still different considerations because their value can include fabrication costs, rarity, design and retail margins.
Consequently, observations about physical gold cannot automatically be applied to every product linked to the metal.
A Portfolio Function, Not a Growth Strategy
The historical record establishes a distinction between gold and productive assets. Equities can generate earnings, bonds can pay interest and property can produce rent. Bullion does not generate an internal cash flow. Its market value rests on scarcity, liquidity and the willingness of governments, institutions and individuals to treat it as a store of value.
That has generally made gold less effective than equities as a principal source of long-term real growth. Its different market behaviour, however, explains why portfolio research frequently considers it as a potential diversifier.
There is no allocation that is suitable for every investor. The relevance of gold depends on an investor’s objectives, time horizon, tolerance for volatility, existing holdings, costs, tax position and the form in which exposure is obtained. Historical diversification benefits do not ensure protection in any particular market episode.
Gold is therefore better understood by reference to its function rather than recent price momentum. It may be considered for resilience or diversification, but it should not be mistaken for an asset that produces income or guarantees protection from inflation and market losses.
The Enduring Insurance Asset
Gold’s continued relevance is partly explained by institutional memory. It has survived repeated changes in political systems, currencies and financial architecture. That durability gives it a psychological and strategic significance that newer financial instruments have not yet replicated.
The present environment has brought those characteristics back into focus. Central banks continue to hold and acquire gold, concerns about fiscal sustainability persist in several major economies and geopolitical competition is reshaping assumptions that supported the post-Cold War financial order.
None of this means that gold will rise continuously. Its history includes sharp advances, severe corrections and extended periods of disappointing returns. An asset capable of preserving purchasing power over generations can still test the patience of holders for decades.
Gold should not be assessed by precisely the same standards as equities or other productive assets because it performs a different economic function. Its relevance tends to increase when confidence in currencies, institutions or financial arrangements weakens.
The “barbarous relic” has endured because the conditions associated with its appeal have never disappeared completely. Currencies can lose purchasing power, geopolitical events can redirect capital flows and governments may seek reserves that are less dependent on another state’s financial system.
Gold remains relevant not because the modern financial system has failed, but because history repeatedly demonstrates that no financial arrangement is permanent.
You may have an interest in also reading…
The Evolution of Elite: A History of Hedge Funds
From Alfred Winslow Jones’s 1949 experiment to today’s trillion-dollar hedge fund industry, the story of hedge funds is one of
The Safety of the System: Why the Restaurant Franchise is Hospitality’s 2026 Safe Haven
In an era of volatile supply chains and discerning diners, the lone wolf restaurateur is an endangered species. As 2026
Small is Beautiful in Banking: Little US Institutions Form a Financial Backbone
Yerbol Orynbayev, former Deputy Prime Minister of Kazakhstan and World Bank governor, reports for CFI.co on the American banking sector.
